
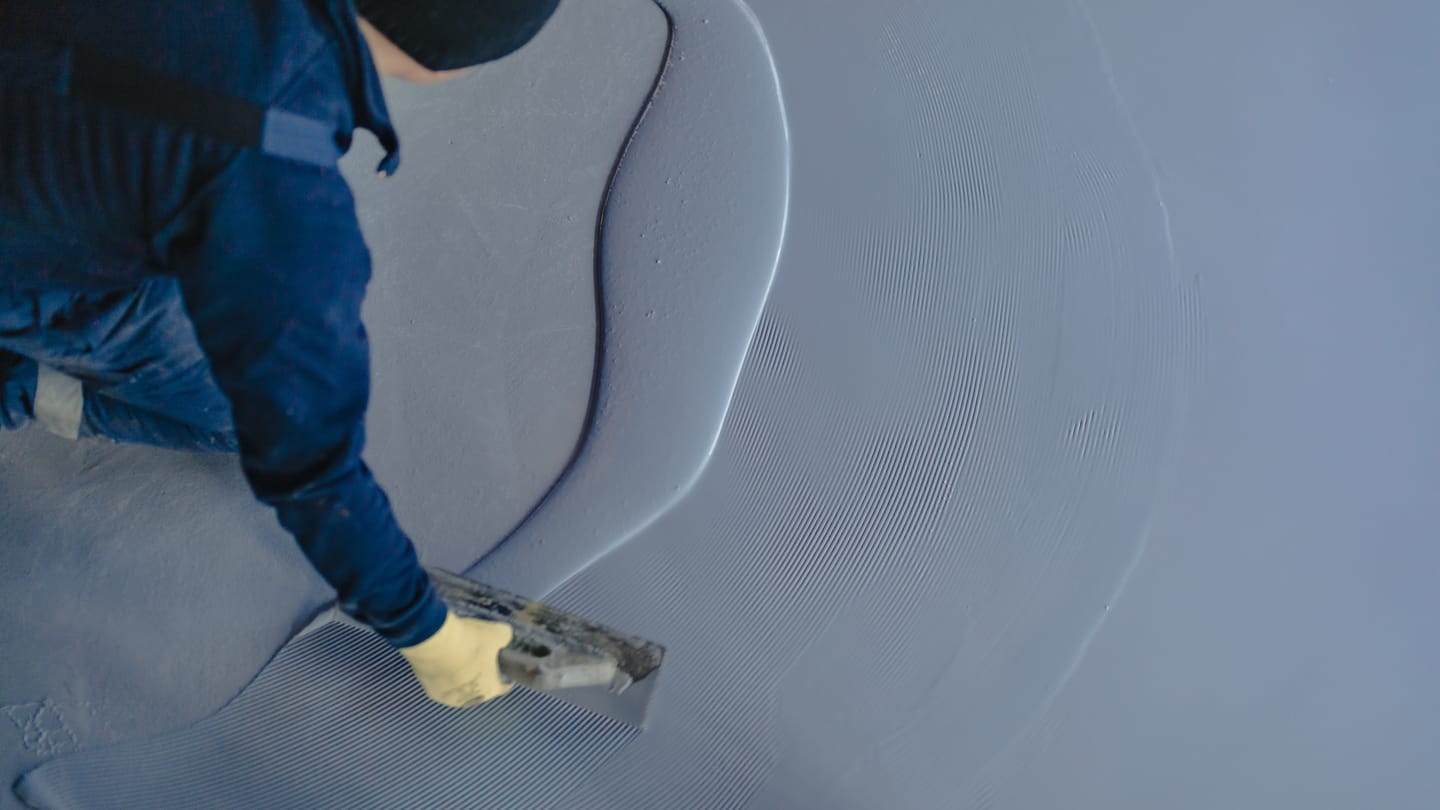
Good epoxy flooring marketing for a new coating business rests on floors people can see and customers who speak about them honestly. Decide who you serve, show finished work, ask for real reviews without paying for praise, and make sure every claim in an ad, including that you are insured, is true on the day it runs.
Who buys a coated floor, and where epoxy flooring leads come from
Your first customers fall into broad groups, so decide which group you are chasing before you spend. Ask yourself where a homeowner who wants a garage or basement floor coated would look for you: a search, a neighbor’s recommendation, a photo on social media. Then ask the same of a commercial buyer, such as a restaurant owner, a warehouse manager or a general contractor: a referral, a bid list, a prequalification form. Build the message, the proof and the paperwork around the answers.
A residential buyer wants to see a finished floor that looks like the floor they picture and to trust that you will show up, protect the driveway and leave a floor that lasts. A commercial buyer wants a crew that can work nights or weekends, that carries the insurance the contract demands and that will not shut the building down longer than promised. Our pages on residential epoxy work and commercial epoxy work cover how each side is insured and what each kind of customer may ask of you.
Epoxy flooring marketing on paper before money goes out
Put your marketing in writing before you spend on it, because a written list of channels and a budget keep you from chasing every pitch a salesperson makes. The Small Business Administration’s guide to marketing and sales puts it plainly: “Marketing takes time, money, and preparation. One of the best ways to stay on schedule and on budget is to make a marketing plan.” In the SBA’s words, a marketing plan “describes the actions you’ll take to persuade potential customers to buy your products or services.”
For an epoxy crew, that means naming the floors you want more of, the towns you will drive to and the reason a customer should pick you. The SBA suggests you “Describe what gives your product or service an advantage over the competition. It might be a better product, a lower price, or an excellent customer experience.” For a coating business, the advantage might be prep you can explain, a coating system you stand behind and a crew that communicates. Write that down in a sentence a homeowner would understand. If you have not settled the company name and registration yet, the business name and registration post covers that step, and how to launch an epoxy flooring business walks through the order of the rest.
Finished floors, photos and the neighbors who notice
Treat every finished floor as advertising, and capture them all. Ask each customer for permission to photograph the floor and to use the photos, and shoot the slab before grinding, during prep and after the topcoat cures. A before-and-after set shows a buyer the work they cannot see in a final photo: the cracks you filled and the surface you ground to sound concrete.
Garage work in particular sells to the neighbors. Ask a satisfied homeowner whether you may leave a yard sign up for a few days, and knock on nearby doors with a card that shows the finished floor. Letter your truck with your name and phone number so every jobsite becomes a billboard. If your state requires a license number on vehicles, include it, as the Florida rule below shows. If the truck is titled or insured personally, ask your agent how commercial auto fits a vehicle that now advertises your business.
Reviews you earn, and the ones federal rules forbid
Ask for reviews from real customers, and know that the Federal Trade Commission sets firm limits on how a business may gather them. Under the FTC’s rule on consumer reviews and testimonials, it is “an unfair or deceptive act or practice and a violation of this part for a business to provide compensation or other incentives in exchange for, or conditioned expressly or by implication on, the writing or creation of consumer reviews expressing a particular sentiment, whether positive or negative”.
The same FTC rule reaches reviews from inside your company: it treats as a violation a business procuring “a consumer review from its officers, managers, employees, or agents, or any of their immediate relatives, for posting on a third-party platform or website” about the business or what it sells, “when the business knew or should have known that the review materially misrepresented, expressly or by implication” that the reviewer exists, that the reviewer actually had experience with the product, service or business, or what that experience was. It also bars a business from seeking to “materially misrepresent, expressly or by implication, that a website, organization, or entity that it controls, owns, or operates provides independent reviews or opinions”. That rules out a so-called independent review page you build for your own company.
What remains is simple. Ask every customer for an honest review, make the request easy with a direct link, answer criticism politely, and fix the problem when a complaint is fair. A real review that mentions a callback you handled well can persuade a buyer more than a page of flawless praise.
Real-World Scenario: A new owner coats a string of garage floors in the same subdivision and wants reviews quickly. A friend suggests offering a discount on a future topcoat to anyone who posts a glowing review, and having the crew’s relatives post a few to get things moving. The owner decides against those ideas, asks each customer for an honest review at the walk-through, and sends a link the same evening. A few reviews mention the cure-time instructions and the clean driveway, and a neighbor calls after reading them.
Endorsements, free floors and the connection you disclose
The FTC’s endorsement guides treat favors and relationships as facts a buyer is entitled to know about. In its Guides Concerning Use of Endorsements and Testimonials in Advertising, the FTC states that “Endorsements must reflect the honest opinions, findings, beliefs, or experience of the endorser” and the guides treat fake positive reviews used to promote a product as endorsements in their own right.
Those FTC guides list what counts as a tie between you and the person praising you: “Material connections can include a business, family, or personal relationship.” They add that such connections “can include monetary payment or the provision of free or discounted products (including products unrelated to the endorsed product) to an endorser, regardless of whether the advertiser requires an endorsement in return.” If you coat a local personality’s garage at no charge in hopes of a post, ask an attorney how that relationship should be disclosed.
The liability does not stop with the person posting. The same guides warn that “An advertiser may be liable for a deceptive endorsement even when the endorser is not liable.” Treat anything a supporter says about your floors as something you said yourself.
Saying you are insured in an ad
Telling customers you are insured is a claim, and it needs a policy behind it that covers the work you are advertising. Florida spells this out in its contracting statute. Under that Florida law, “a local government may impose a civil fine” against a person who is not certified or registered under the contracting part if the person “Claims to be insured in any offer of services, business proposal, bid, contract, or advertisement, but whose performance of the subject work is not covered by a general liability or workers’ compensation insurance policy.”
The Florida statute also governs license numbers in advertising. For Florida-registered or certified contractors, it says “The registration or certification number of each contractor shall appear in each offer of services, business proposal, bid, contract, or advertisement, regardless of medium, as defined by board rule, used by that contractor or business organization in the practice of contracting.” It reaches lettered trucks as well, and it notes that an advertisement “does not include business stationery or any promotional novelties such as balloons, pencils, trinkets, or articles of clothing.”
That is Florida’s rule, not a national rule. Whether floor coating needs a Florida license at all is a separate question; our Florida page covers it. Wherever you work, check what your state asks of contractor ads, and ask your agent whether your general liability and workers compensation policies cover the floors your ads describe before the word “insured” goes on a sign.
Winning a commercial buyer: certificates and references
Be ready to show a commercial customer proof of insurance and experience before your crew sets foot in the building. Ask each prospect up front whether it wants a certificate of insurance, whether it wants to be named on your policy, and which references from similar jobs it would call. Gather those before you bid, not the night before mobilizing, because a slow answer can cost you the job.
Build a short packet: photos of commercial floors you have coated, references who will take a call, a description of how you handle dust, odor and cure time in an occupied building, and your license information where your state or city requires it. Ask your agent which certificate wording your policies can support, since a certificate describes coverage and does not add any. A contract that calls for higher limits may point you to umbrella liability, and our overview of what an epoxy coating business insures covers the rest of the program a commercial buyer will ask about.
Measuring what each channel brings back
Track every lead from the first call to the paid invoice, so you know which channels earn their cost. The SBA advises owners to “compare your marketing and sales costs to the revenue it generates” to be sure of “a positive return on investment, or ROI.” Ask every caller how they found you, record it, and review the list against the jobs that paid.
The SBA also says “Marketing plans should be maintained on an annual basis, at minimum.” Review yours on a schedule, drop what brings nothing, and put more behind the referrals, reviews and contacts that fill your calendar with floors you want. When the work grows, request a quote with your payroll, vehicles and job mix so your coverage grows with it, or read about us and how we work with coating businesses.